Overview
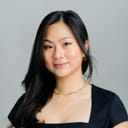
Emily Man is a Partner at Primary Venture Partners focused on Fintech & Enterprise AI investments[1]. Man leads investments in early stage companies spanning pre-seed through Series A across enterprise software and fintech[4]. Man holds a Bachelor of Arts in Financial Economics with a concentration in Business Management from Columbia University[13]. Beyond the partner role, Man serves on the boards of Caspian, Circuit & Chisel, and Maybern[6][7][8], and maintains investor positions in companies including Ramp and FloQast[10][11], alongside angel investing activities across various startups[12].
Profile introduction
I lead investments in early stage (pre-seed through Series A) companies across enterprise software and fintech. If we haven't met please include a short message in your connection request!
Career history
- Partner2023 to PresentPrimary Venture Partners
- Board Member2025 to PresentCaspian
- Board Member2025 to PresentCircuit & Chisel
- Board Member2024 to PresentMaybern
- Board2023 to PresentCasap
- InvestorMar 2021 to PresentRamp
- InvestorJul 2021 to PresentFloQast
- Angel InvestorSep 2020 to PresentVarious Startups


Education
Bachelor of Arts - BA, Financial Economics; Concentration in Business ManagementColumbia University

Insights & ideas
The through-line
Emily Man came into venture from a world of models, coverage universes and basis points, and the lesson she keeps returning to is that the quantitative work is the easy part. "The number one biggest lesson that I learned and that I continue to carry to this day is and it's gonna sound so cheesy but it's that the people are really what matter at the end of the day" [1]. She frames this as a correction to her own early instincts: coming from a background that was "very quantitative" and "very research driven" meant she "would underweight the importance of the people" [1]. Her worked example is Square around 2017 and 2018, where everyone in the investing industry implicitly knew that CFO Sarah Friar was a driver of the business, but that knowledge "wasn't quantified in any way in our like models or approach or thesis" [1]. When Friar announced her departure, the stock dropped ten percent [1].
The second constant is a resistance to received categories. She dislikes "fintech" as a label because "an insurance broker is totally different from a bank is totally different from a lender" [1], and she is equally sceptical of the shorthand the venture industry uses to sort founders. Both objections come from the same place: the label hides the variable that actually drives the outcome. Her stated preference is for "going deep into unsexy industries" and backing founders challenging the status quo [2].
On what makes a founder worth backing
At the earliest stage, she argues, there is nothing else to underwrite. "Oftentimes the companies that we're investing in have no traction they have no product like all they have is like this a team and a set of ideas," so however much work you do on the market and the business, "at the end of the day if the people aren't right it's not going to work" [1]. The criterion she and Primary apply is learning rate rather than credentials: "we're looking for people who are learning machines," and what matters is "not that you come with all the answers and the background and the knowledge it's just like what is the rate at which you can absorb information and demonstrate like a level of continuous improvement," which she calls "by far in a way the biggest driver of long-term success" [1].
Paired with that is resilience. Many of the successful founders in the portfolio "have gone through significant hardships" personally or professionally and persevered [1]. Her reasoning is specific about failure modes: before product market fit, companies do not usually die because they run out of money or the market was not there, but "because you know either the co-founders fight or the founders or the team gives up" [1]. She is pointed about the alternative filter the industry defaults to. Pedigree is "one fallacy that the venture industry kind of sometimes over indexes to," visible on Twitter as optimising for a particular Ivy League school or a particular famous employer, and the cost is that "a lot of people who would be extremely successful founders get overlooked," particularly "if they're not a white guy who speaks really quickly," a pattern she says shows up in the funding statistics for women and minorities [1]. The evidence she cites for the non-obvious bet is Primary's own fund one, where roughly 30 percent of companies became unicorns, and yet "if you like peel back the layers of the onion and you look at those teams like a lot of them were not obvious bets" [1]. She has also spoken about the gender gap in venture itself and about advice for people trying to break into investing [4].
On why fintech resists being treated as one thing
Her objection to the category is practical as well as taxonomic. In consumer investing, she says, the data is abundant: you can buy anonymised credit card panels that tell you whether spending at Walmart is up month on month [1]. Fintech is harder because the businesses inside the label have little in common and are "very much more tied to the macro" [1]. So the research shifts to interest rates, what the Fed is signalling about different markets, and what regulators are likely to investigate or crack down on, work that at Point72 was supported by dedicated in-house people [1].
She has watched the sector's reputation swing through a full cycle in her own career: when she started, people said "okay you do that like it's not that interesting to me," then it became "really really popular" in the hype cycle, and now it is "in a rout" with headlines asking whether fintech is dead [1]. Her counterweight is a statistic she cites approvingly, that roughly 20 percent of today's unicorns are fintech companies, the second largest category after the "nebulous enterprise tech" [1]. She continues to believe "there's like tons and tons of opportunity in a bunch of different spaces" [1].
On where the opportunity actually is
She names three areas. Payments first, on the grounds that digitisation is barely underway: "there's like I don't know still trillions of dollars that transact over ACH and check today and those are not what those things were originally intended for," and the magnitudes of outcomes available in payments "are massive" [1]. Her example is Ana, founded by Sophia Goldberg and her co-founder JT, which builds white label wallet infrastructure for quick service and other businesses, modelled on the preloaded Starbucks wallet that generates something like four billion dollars of float a year and functions, in her words, like a bank while driving loyalty and visit frequency [1]. Red Bay Coffee is one of their customers [1].
Second is what she loosely calls CFO software: products selling into the office of the CFO, including risk advisory on both the corporate and market sides [1]. The specific pull she has been excited about for a long time is smaller and mid-market businesses wanting "a holistic one-stop shop" for their back office finances, the thesis behind her investment in Ramp while she was at Redpoint [1]. Third is what she calls banking tech for want of a better word: software sold into traditional financial institutions that have realised they need to catch up on technology and "are probably not going to be able to build it themselves," so they buy from third-party vendors [1]. That spans account opening, compliance, risk software and capital markets software on the back end, and she would bundle parts of legal tech into the same bucket [1]. Payments and capital markets are the areas she has highlighted as current enthusiasms at Primary [4], alongside the future of AI in fintech and broader enterprise software trends [2].
On doing the research
Her method for getting up to speed on an industry has three layers. First, public company information: 10-Ks, 10-Qs, investor days [1]. Second, sell-side and industry research, the tear-downs produced by investment banks' equity research arms, read both to ramp and to stay current [1]. Third, and the one she treats as the differentiator, proprietary research and data, which Point72 invested behind heavily [1]. That meant an internal market intelligence team that would, for instance, call a hundred truckers to establish how pricing had moved month on month and year on year in order to model the effect of rising trucking costs on Campbell Soup [1]. It also meant purchased external datasets, and analysis she did herself. Covering Chipotle, where net new store openings is an important driver and good data did not exist, she "built a scraper" to count the locations listed on the company website and revisit the same script a week or a month later to measure the delta [1].
The output of all this was never the model itself. The analyst's job, as she describes it, was to build the model, go deep on the company, meet management, understand the drivers "down to like a fraction of a basis point," and then "identify the debates" around the name, form a view on where it trades over the next three to twelve months, and pitch it to the portfolio manager when conviction was high enough [1]. That habit of thesis-driven work is what she says drew her to early stage investing, where "you can apply a lot of like deep thesis driven thinking" [1].
On technology adoption and financial inclusion
Her interest in the sector traces to moving to Beijing at twelve and watching the transition first-hand: "when I first moved back to Beijing it was like cash based society everything was analog and then by the time I left it was the super apps rule them all," with everything ordered online arriving within two days [1]. She calls it the best available case study for "what viral rapid adoption of technology could look like in a short span of time" [1]. What she took from it was not only speed but distribution, since technology reshaped society and brought in "groups that otherwise would have been marginalized or left out of the financial ecosystem" [1]. That interest in globalisation, technology and inclusion is what she went into undergraduate study wanting to pursue, before taking the traditional New York route into finance [1].
On how venture careers actually begin
She is candid that she had the wrong picture of the job. "I honestly up to that point I thought that like venture was something that you did when you were 60 years old and like retired from your exec job at Cisco and you like wanted to sit around a table and tell people no" [1]. What changed it was a colleague, Pete Casella, brought in to build an internal venture strategy, who told her he thought she had "a really good nose for this venture thing" and invited her to build the practice with him, an offer she describes as running "a startup within a larger" firm [1]. She has also spoken about the strategies that helped her manage transitions within venture as she moved between firms [4]. On leaving the hedge fund, she is clear that it was not a repudiation: the role "created a really great foundation of skills that I've continued to rely on and bring into my day-to-day" [1].
Takeaways
- At pre-seed and seed, the only real underwriting is the team, because the company typically has no traction and no product [1].
- Screen for learning rate and resilience rather than credentials: the question is "what is the rate at which you can absorb information," not what you already know [1].
- Pedigree filters cost the industry good founders, disproportionately those who are not "a white guy who speaks really quickly" [1].
- Early stage companies usually fail because co-founders fight or the team gives up, not because the money or the market ran out [1].
- Treat "fintech" as a false category: brokers, banks and lenders behave differently, and the common variable is macro, meaning rates, the Fed and regulators [1].
- Three areas of concentrated opportunity: payments, where trillions still move over ACH and check; CFO software for the small and mid-market back office; and software sold into traditional financial institutions that cannot build it themselves [1].
- Roughly 20 percent of current unicorns are fintech companies, the second largest category, which is the counterargument to "is fintech dead" [1].
- Build proprietary data when it does not exist, whether that means calling a hundred truckers or scraping a restaurant chain's store locator week over week [1].
Media & appearances
- Women in Venture CapitalApple PodcastsA Conversation with Emily Man, Partner at Primary Ventures | Redpoint Ventures | Point72 Ventures | Columbia UniversityIn this conversation with Emily, we touched on the experiences that shaped her move to and career in venture capital, including the rapid transformation in areas like Fintech. Emily shares more about strategies that helped her manage transitions within VC and trends she's excited about at Primary including innovations in payments and capital markets. Finally, Emily touches on bridging the gender gap in venture and shares some advice for aspiring investors.
- Venture with GraceApple PodcastsEmily Man: Navigating Fintech Frontiers at Primary VenturesEmily is a Partner at Primary, leading new investments in fintech and enterprise software companies. She loves going deep into unsexy industries and partnering with determined founders who are challenging the status quo. Before Primary, Emily was at Redpoint Ventures investing across early and growth stage companies. She started her career as a hedge fund analyst at Point72 before helping build Point72 Ventures, the early stage venture practice. Emily earned her BA from Columbia University where she graduated summa cum laude. Topics: - The Future of AI in Fintech - Trends in Fintech and Enterprise Software - Opportunities and Challenges in Investing in Fintech #FintechInvesting #DigitalPayments #EmergingMarkets #FintechPartnerships #FintechTrends
- Grace GongYouTubeEmily Man: Navigating Fintech Frontiers at Primary VenturesEmily Man discusses her career path from hedge fund analyst at Point72 to venture investor, her early exposure to rapid technology adoption in China, and her investment thesis around fintech and unconventional founders. She explains her role covering consumer, CPG, luxury, and payments sectors as an analyst, and how she transitioned into venture strategy before joining Primary Venture Partners.
- Front and Center PodcastYouTubePentagram Ain’t Nuthing ta F’ Wit: with Emily ObermanWe got Emily Oberman on the program! She is a Partner at Pentagram and perhaps best known for her work in the entertainment industry. Emily has designed the ...
- SpotifyA Conversation with Emily Man, Partner at Primary Ventures - Spotify
This page shows public professional information only, each fact cited. Is this you? send a correction, or ask for removal within 24 hours, no questions asked.